Valuation services

Valuations of plant, infrastructure, property and businesses

Reliable, well-supported valuations for every purpose — plus the asset registers and tagging that keep your asset data accurate.

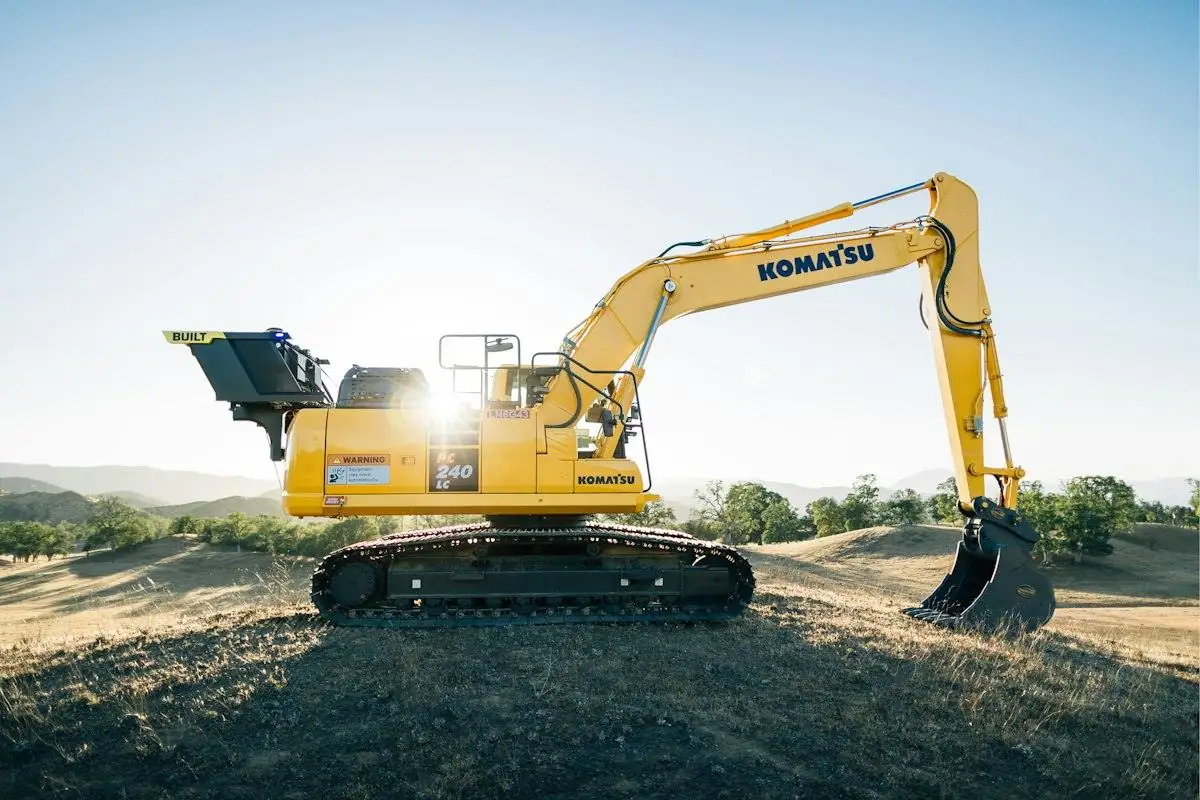
Plant & equipment valuations

Valuations of machinery and equipment for reporting, insurance, transactions, lending and disputes.

More on plant and equipment valuations Request a quote

Typical purposes

  • Fair value for financial reporting
  • Replacement or reinstatement cost and indemnity value for insurance
  • Market value for buying or selling a business or its assets
  • Recoverable amount for impairment testing — fair value less costs to sell, or value in use
  • Fair value for business combinations (mergers and acquisitions)
  • Fair value for purchase price allocations
  • Market or liquidation value for loan security and asset finance
  • Orderly or forced liquidation value for insolvency and liquidation
  • Market value for in-kind capital contributions
  • Market value for dispute resolution

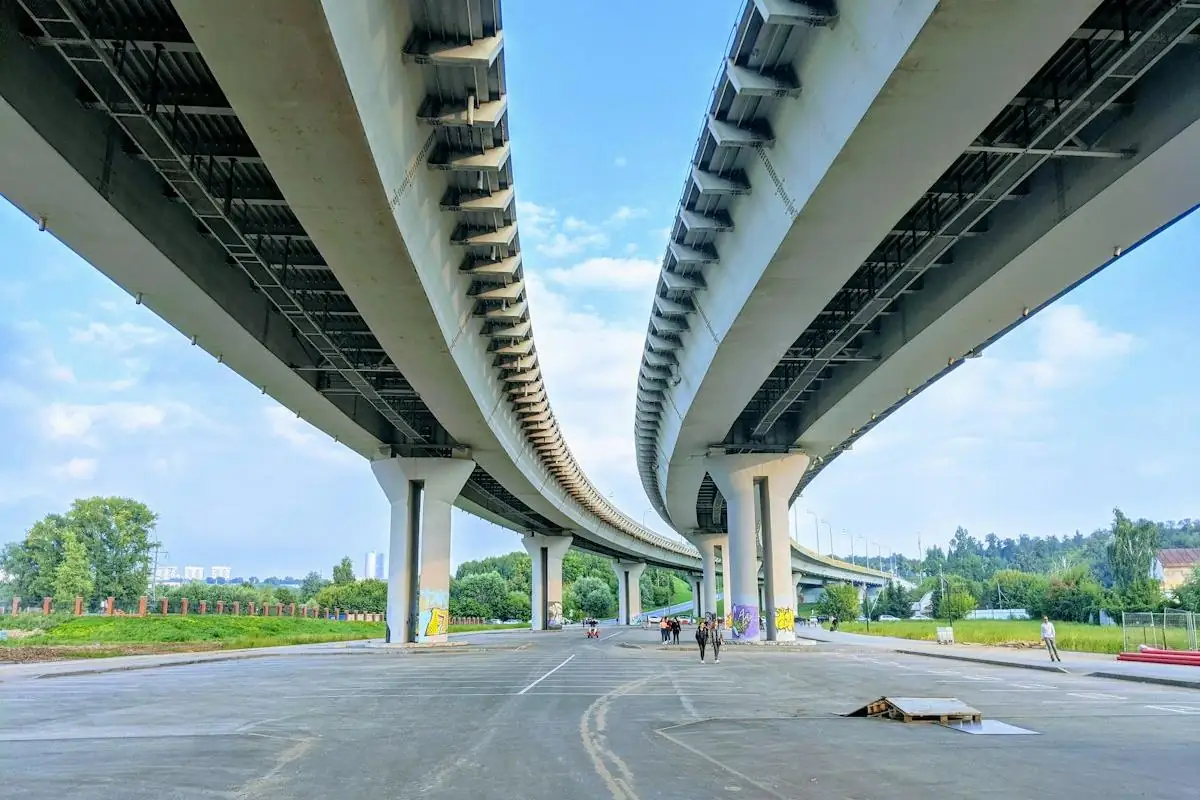
Infrastructure valuations

The economic value of the structures, systems and facilities that provide essential services.

More on infrastructure valuations Request a quote

Assets we value

  • Roads, bridges and footpaths
  • Airports
  • Water and sewerage systems
  • Energy facilities
  • Telecommunications networks

What we take into account

Infrastructure assets usually have long useful lives, often spanning decades. We consider both their tangible and intangible aspects, including depreciation and future maintenance costs, the policies, regulations and permits that govern the asset, and its replacement cost and residual value at the end of its life.

Typical purposes

Investment, financing, divestment, asset management, timing asset replacement, and financial reporting.

Real estate & building valuations

Land and building valuations for sales, insurance, taxation, financing and investment decisions.

Request a quote

Land

  • Location and size
  • Zoning regulations
  • Development potential
  • Highest and best use

Buildings

  • Age, size and construction quality
  • Design and functionality
  • Condition and obsolescence
  • Market demand, accessibility and nearby amenities

We apply standardised valuation methods and take prevailing economic conditions into account, so our valuations are accurate and reliable.

Business valuations

Whole-of-business valuations for sales, mergers and acquisitions, investment decisions, restructuring and tax reporting.

More on business valuations Request a quote

How we arrive at a value

Our business valuers apply several methods and cross-check them against each other, so the value we report for your company is robust.

Methods we use

  • Discounted cash flow analysis
  • Market capitalisation
  • Enterprise value
  • Earnings-based methods
  • Present value of a growing perpetuity
  • Book value

Asset register creation

An accurate asset register is the foundation of every asset management decision.

More on asset registers Request a quote

Why it matters

  • Know exactly which assets you own
  • Capture each asset's key characteristics
  • Keep the register up to date easily
  • Make verification simple for auditors
  • Keep effective maintenance records

What a register typically records

Asset number, location, description, attributes and specifications, and components. A good register is simple, practical and easy to update, and makes it easy to record maintenance history.

Asset coding & tagging

Track your physical assets with RFID tags, barcodes and GPS trackers.

More on asset tagging Request a quote

Information you can capture

  • Asset class or category
  • Real-time location
  • Asset users
  • Purchase history and cost
  • Depreciation charges and revalued fair values
  • Maintenance schedules
  • Condition, useful life and remaining useful life

The benefits

Tagging saves time and resources when locating assets and equipment, and reduces the costs of loss and theft. Our experienced valuers collect the right data for your assets and set up a coding system that works for your organisation.

How we work

Our 20-step valuation process

Every valuation follows the same structured process, designed for transparency, accuracy and compliance with the International Valuation Standards — from your first enquiry to the final report.

Stage 1 · Steps 1–4

Scope & proposal

  1. Contact us with your requirements at assets@business-assets-valuers.com.
  2. Discuss your requirements with our team and agree the scope of work.
  3. Send us any relevant asset registers or asset lists.
  4. Sign the valuation proposal setting out the agreed scope, fees and deliverables.

Stage 2 · Steps 5–9

Inspection

  1. We assign a valuer experienced and specialised in your asset type and area.
  2. The valuer arranges a pre-inspection or physical inspection of the assets.
  3. The valuer collects any further information needed, such as drawings and contracts.
  4. The valuer inspects the assets, recording make, model, serial and registration numbers, capacity, dimensions, year of manufacture and condition.
  5. We reconcile your asset register with the inspection data to produce the valuation asset register.

Stage 3 · Steps 10–15

Valuation

  1. Where needed, we research replacement costs and comparable sales for identical or similar assets.
  2. We research economic lives, total useful lives and residual values.
  3. Where needed, we adjust replacement costs for installation, freight, transport and commissioning.
  4. We adjust comparable sales for age, location, condition, usage and similarity.
  5. Where needed, we quantify physical, technical and economic obsolescence and calculate depreciated replacement cost.
  6. We assign fair or market values from the adjusted comparable sales or the depreciated replacement cost.

Stage 4 · Steps 16–20

Report & review

  1. We write a comprehensive valuation report that complies with the International Valuation Standards.
  2. A director or senior valuer reviews the report against our quality checklist to confirm it meets IVS requirements.
  3. We send you a draft report for review.
  4. We answer your questions and amend the report as needed.
  5. We issue the final report.

Methodology

Valuation approaches

The right approach for each assignment depends on the purpose of the valuation, the basis of value and any other relevant assumptions. The three principal approaches are the market, cost and income approaches.

The market approach indicates value by comparing the asset with identical or comparable (similar) assets for which price information is available. It uses prices and other information from market transactions involving identical or similar assets, liabilities, or groups of assets and liabilities, such as a business.

It is the primary approach when:

  • The asset has recently been sold in a transaction appropriate for the basis of value.
  • The asset, or substantially similar assets, are actively and publicly traded.
  • There are frequent or recent observable transactions in substantially similar assets.

Comparable transactions method

The comparable transactions (sales comparison) method is the most common way to apply the market approach:

  1. Identify the units of comparison used by participants in the relevant market.
  2. Identify relevant comparable transactions and calculate their key valuation metrics.
  3. Consistently compare the qualitative and quantitative similarities and differences between the comparable assets and the subject asset.
  4. Adjust the valuation metrics, if needed, to reflect those differences.
  5. Apply the adjusted valuation metrics to the subject asset.
  6. If several valuation metrics were used, reconcile the indications of value.

Choosing comparable transactions

  • Evidence from several transactions is generally better than a single transaction or event.
  • Transactions in very similar (ideally identical) assets give a better indication of value than those needing significant adjustment.
  • Transactions closer to the valuation date better represent the market at that date, particularly in volatile markets.
  • For most bases of value, transactions should be at arm's length between unrelated parties.
  • There should be enough information about each transaction to understand the comparable asset and assess the evidence.
  • Information should come from a reliable, trusted source.
  • Actual transactions are better evidence than intended transactions.

The cost approach is based on the economic principle that a buyer will pay no more for an asset than the cost of obtaining one of equal utility, whether by purchase or construction, unless undue time, inconvenience, risk or other factors are involved. It indicates value by calculating the current replacement or reproduction cost of an asset, then deducting physical deterioration and all other relevant forms of obsolescence.

It reflects the amount currently needed to replace the service capacity of an asset, often called its current replacement cost.

Common cost elements

  • Direct costs: materials and labour
  • Indirect costs: transport, installation, professional fees, overheads, taxes, finance costs and profit margins

Replacement cost method

Replacement cost is the amount needed to replace the entire property with one of like utility and function, based on current market prices for materials, labour and equipment, plus the contractor's overheads, profit and fees. It excludes overtime, bonuses and premiums on materials.

Fair value is estimated as replacement cost less accumulated depreciation caused by obsolescence. See our guide to the depreciated replacement cost method, with a worked example.

Reproduction cost method

Reproduction cost is the amount needed to reproduce an exact replica of the entire property. Where replacement cost considers like utility and function, reproduction cost considers like kind and materials. It is appropriate when:

  • A modern equivalent asset would cost more than recreating a replica of the subject asset.
  • The utility of the subject asset could only be provided by a replica, not a modern equivalent.

Fair value is estimated as reproduction cost less accumulated depreciation caused by all forms of obsolescence.
The income approach indicates value by converting future cash flows into a single current value. The value of the asset is determined by the income, cash flow or cost savings it generates.

It is the primary approach when:

  • The asset's ability to produce income is the critical factor affecting its value from a market participant's perspective.
  • Reliable projections of the amount and timing of future income are available, but there are few, if any, relevant market comparables.

Get started

Request a valuation quote

Tell us what needs valuing and why. We'll agree the scope with you and send a proposal covering scope, fees and deliverables.

Required

Call Get a quote